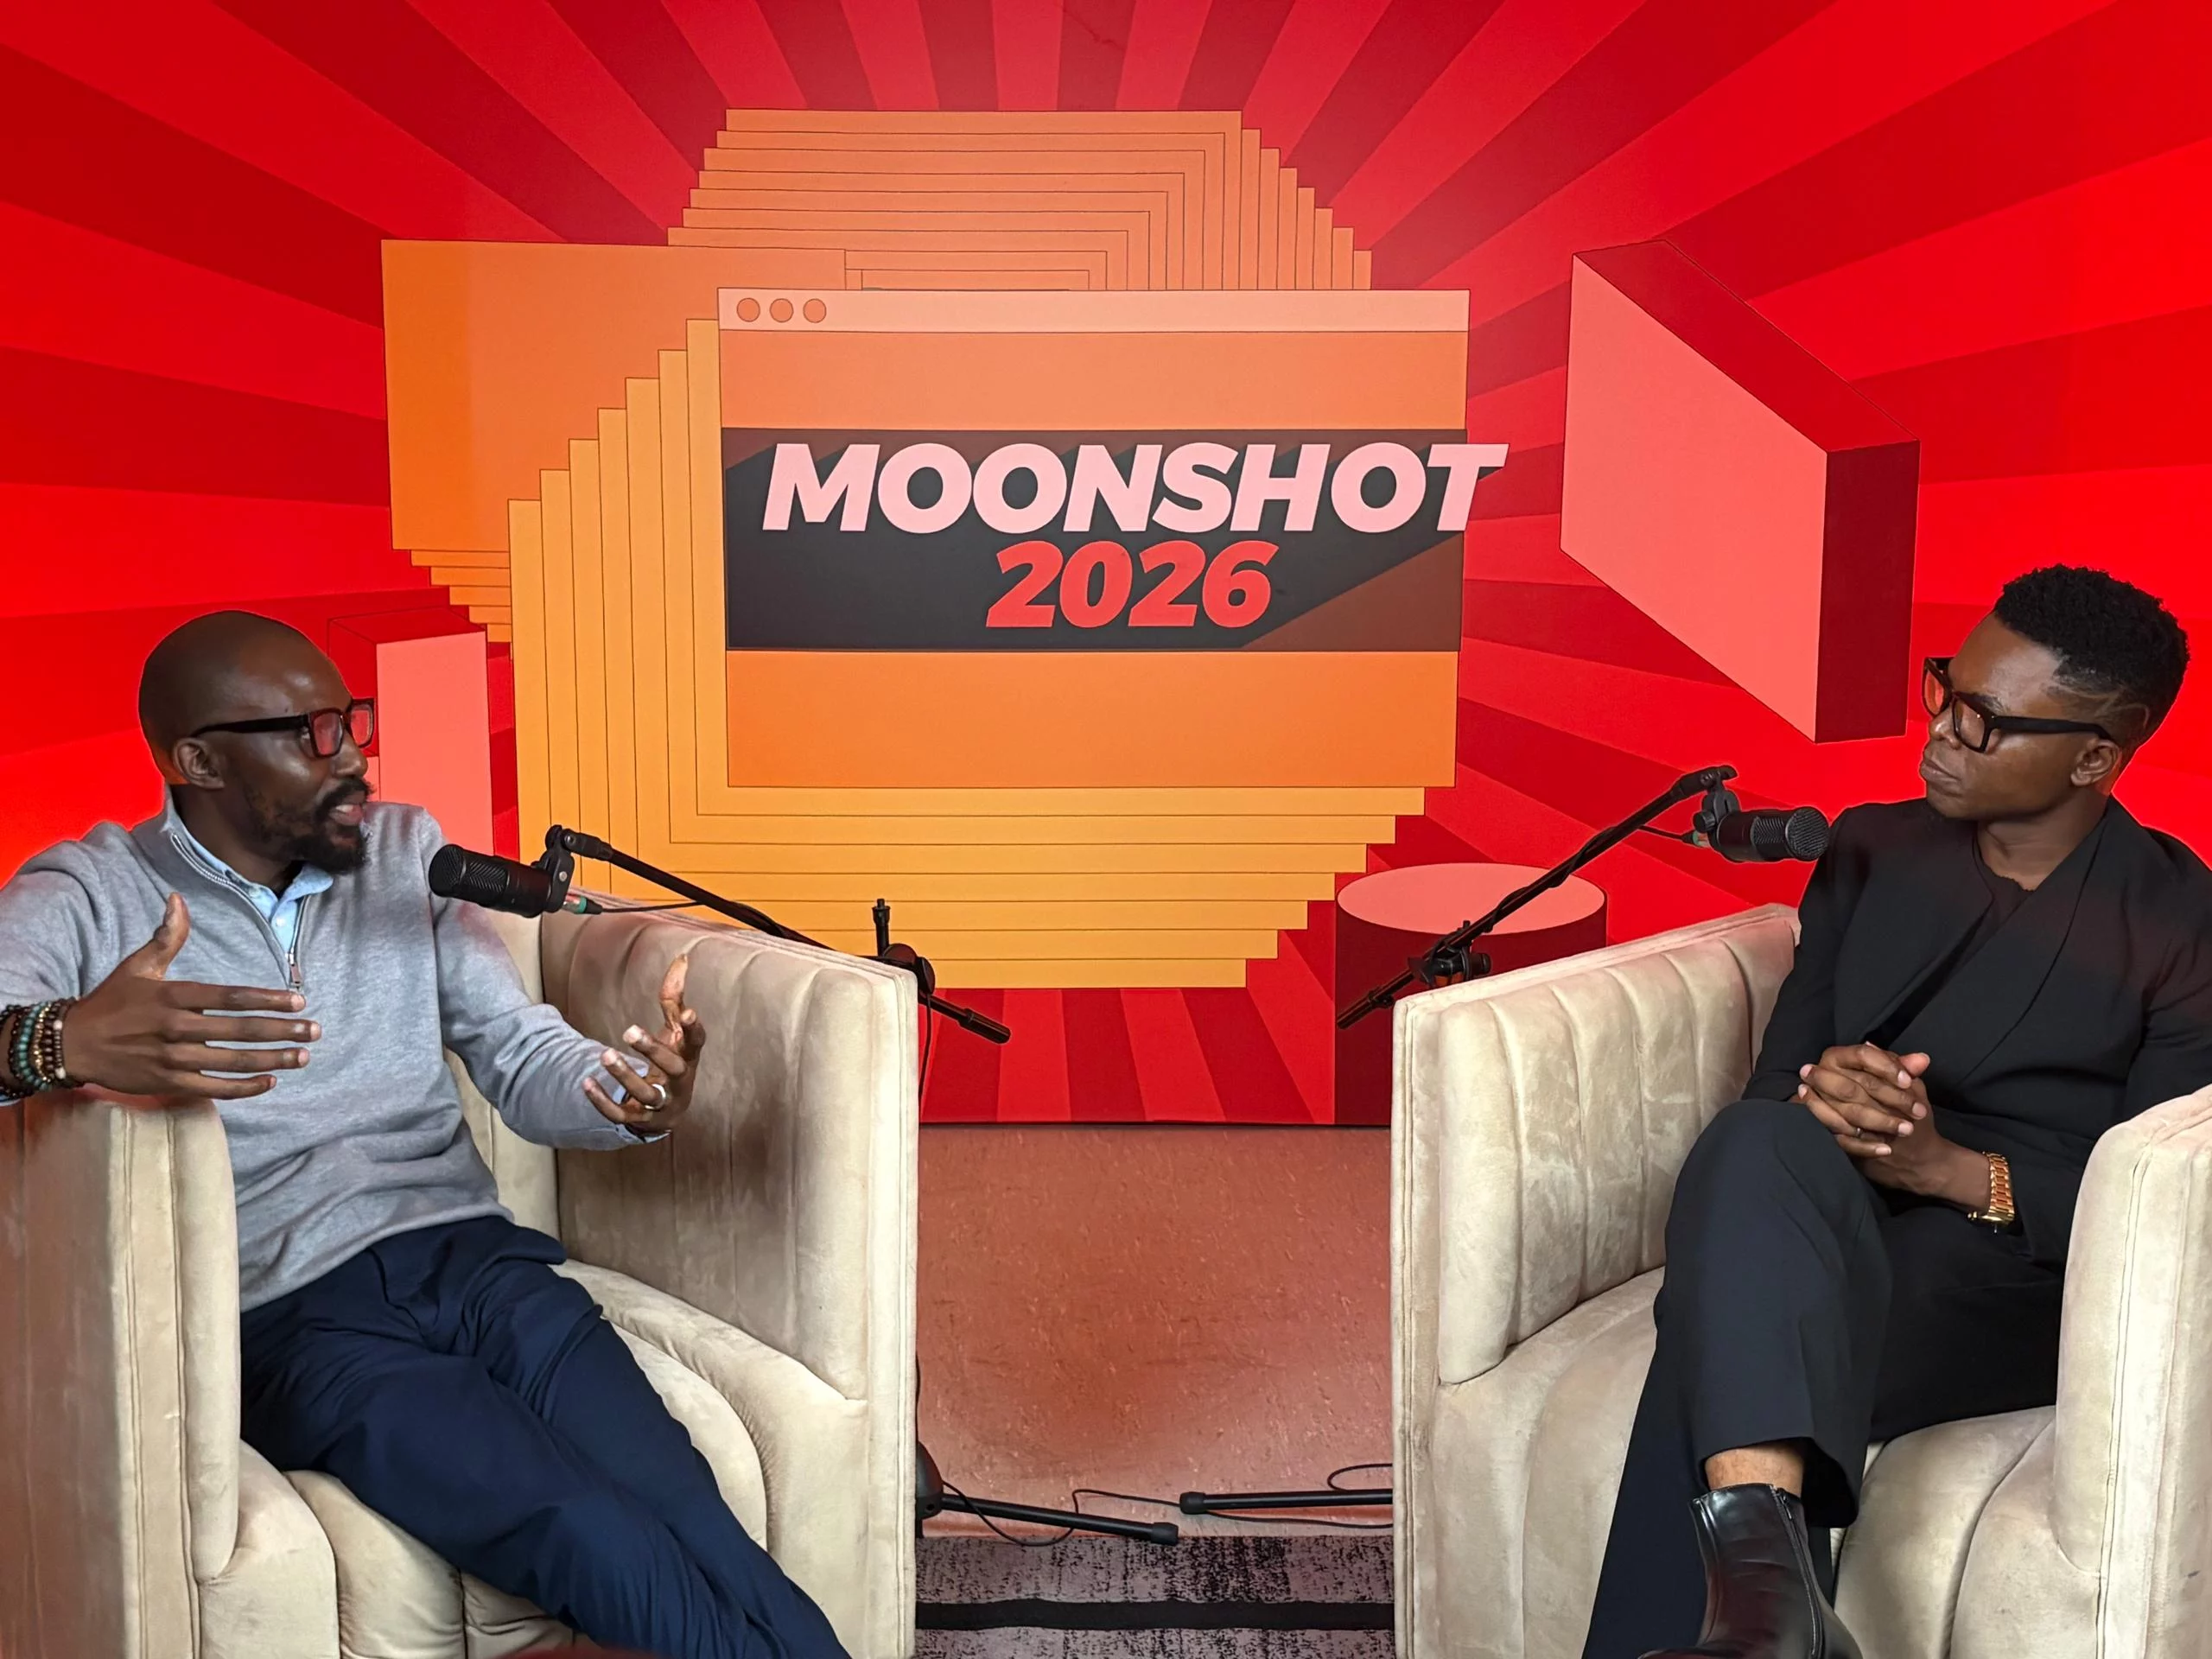
Interswitch, Nigeria's premier payments technology company, is intensifying efforts to mainstream tap-to-pay across the country. While banks and merchants have begun preparing the necessary infrastructure, adoption among consumers has been slower than expected, and the company points to a lack of awareness as the primary obstacle.
Introduction
Interswitch is driving a continent-wide push to normalize contactless payments, leveraging bank partnerships, merchant onboarding, and consumer-focused content to bridge the adoption gap.
What Happened
At Moonshot 2026 in Lagos, Interswitch's Tomi Ogunlesi stated that major banks including GTBank Wema Bank ProvidusUnity Zenith and FirstBank are equipped to support tokenised tap-to-pay transactions. The company is also working with merchants such as Spar and has partnered with Mastercard to launch Google Pay for Nigerian Android users. Historical context includes the 2015 PayAttitude launch Access Bank's 2025 Tap to Phone service and a recent CashAfrica-Chicken Republic partnership that expanded contactless access to over 350 outlets. Despite these steps tap-to-pay has yet to achieve mainstream status in Nigeria largely due to infrastructure limitations and low consumer familiarity.
Why This Matters
The success of tap-to-pay hinges on consumer trust which Interswitch aims to build through tokenisation - a process that replaces a card's primary account number with a one-time digital token for each transaction. Ogunlesi explained that this mechanism ensures sensitive card details are never exposed during a payment. To drive understanding the company is distributing a 15-minute documentary titled Are You Tapping which traces the evolution of payments in Nigeria and explains how tokenisation protects users. Ogunlesi also noted that Nigeria's earlier transition from magnetic-stripe to EMV chips prompted by a 2009 Central Bank directive established a foundation that fintechs and banks are now leveraging. While physical cards still offer advantages for international transactions and dispute resolution the industry is exploring digital-asset infrastructure to enable faster cheaper cross-border payments.
Key Takeaways
- Banks and merchants have the infrastructure ready but consumer adoption remains the central challenge.
- Tokenisation is the security feature designed to instill confidence in contactless payments.
- Interswitch is using documentary content and partnerships to educate Nigerian consumers.
- The 2009 shift from magnetic-stripe to EMV chips created the current payment ecosystem foundation.
- Physical cards are expected to evolve but the underlying payment rails will continue to play a critical role.
Conclusion
Interswitch is positioning itself as the driving force behind tap-to-pay's transition from niche to mainstream in Nigeria. By combining bank collaborations merchant onboarding and targeted consumer education the company aims to overcome the trust gap that has slowed adoption. As the payments landscape evolves the focus will shift from proving the technology works to ensuring every Nigerian feels confident tapping to pay.


Discussion
Join the conversation
Thoughtful reactions, questions, and follow-up ideas help shape the next story.