Introduction
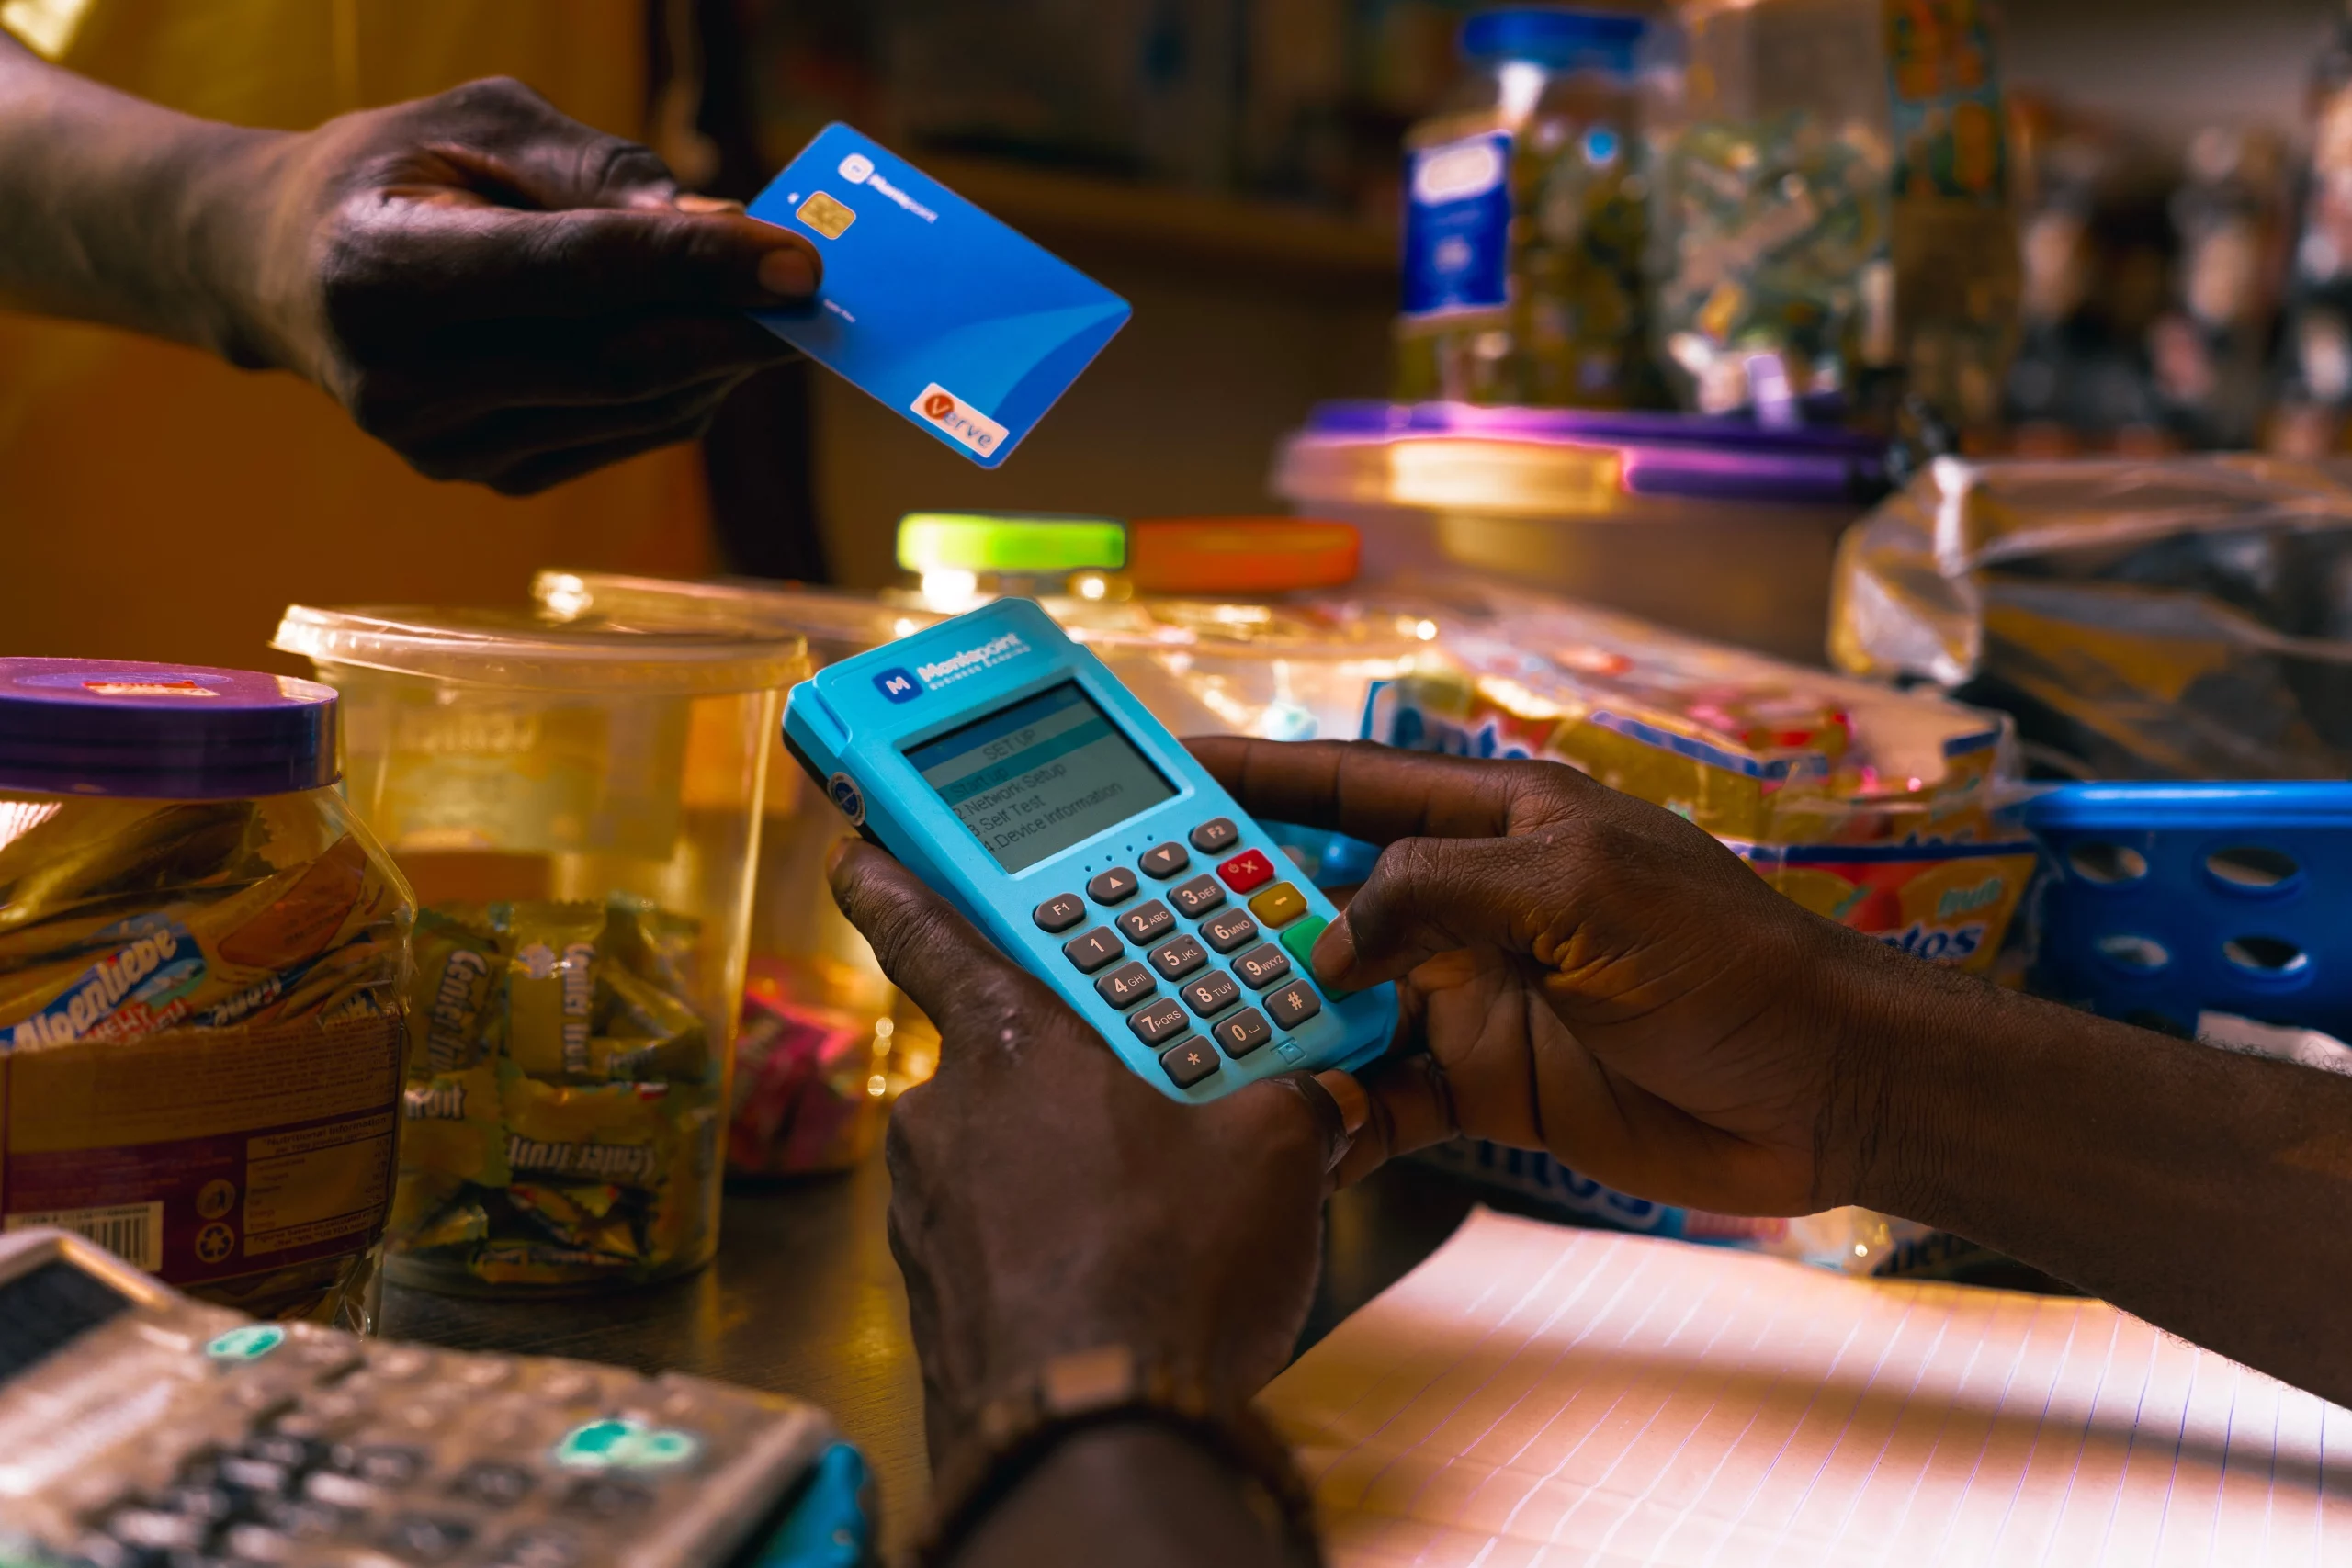
Moniepoint UK Limited, the British arm of Nigeria's fast-growing fintech unicorn, has released its first financial snapshot since migrating customers from its diaspora remittance product, MonieWorld. The figures offer a rare glimpse into how the company is monetising its UK expansion while reassessing its broader market strategy.
What Happened
In December 2025, Moniepoint completed the migration of MonieWorld customers into its newly regulated UK entity, Moniepoint UK Limited. The $36,284 in revenue reported for 2025 reflects just one month of activity under the new structure. The company acquired Bancom Europe Limited in July 2025, securing an FCA-authorised electronic money institution licence that enabled it to operate independently of third-party payment facilitators.
Before the migration, MonieWorld operated under Moniepoint GB Limited without its own EMI licence, relying on PayrNet Limited to process UK transactions. The acquisition gave Moniepoint direct regulatory standing, though the MonieWorld brand has since been discontinued as the company shifts focus to its core African business platform.
Why This Matters
The modest revenue figure underscores the challenges of establishing a regulated presence in a competitive UK-Nigeria remittance corridor already crowded with players like LemFi and Sendwave. Moniepoint's move highlights how fintechs must balance regulatory compliance, cost structure, and market timing when expanding across borders. The discontinuation of MonieWorld, despite 70% monthly transaction growth, signals a strategic realignment toward higher-impact areas of the African payments ecosystem.
Key Takeaways
- Moniepoint UK generated $36,284 in revenue within one month of migrating MonieWorld customers into its regulated entity.
- The company reported a $226,172 loss after tax for the full year, with $10,220 in gross profit.
- Technology and communication emerged as the largest administrative expense at $125,838, while foreign-exchange fees and bank partner fees formed the core cost of sales.
- The acquisition of Bancom Europe, funded by a $2.51 million equity deposit, granted Moniepoint its own FCA-authorised EMI licence.
- MonieWorld's rapid growth notwithstanding, the product was discontinued to prioritise Moniepoint's platform for African businesses.
Conclusion
Moniepoint's first UK financial report is less about immediate profitability and more about strategic repositioning. The company has secured regulatory footing, migrated its diaspora user base, and chosen to redirect resources toward its core African operations. For observers of the African fintech landscape, it's a case study in how quickly a cross-border product must evolve when faced with competition, compliance costs, and shifting long-term priorities.


Discussion
Join the conversation
Thoughtful reactions, questions, and follow-up ideas help shape the next story.