Introduction
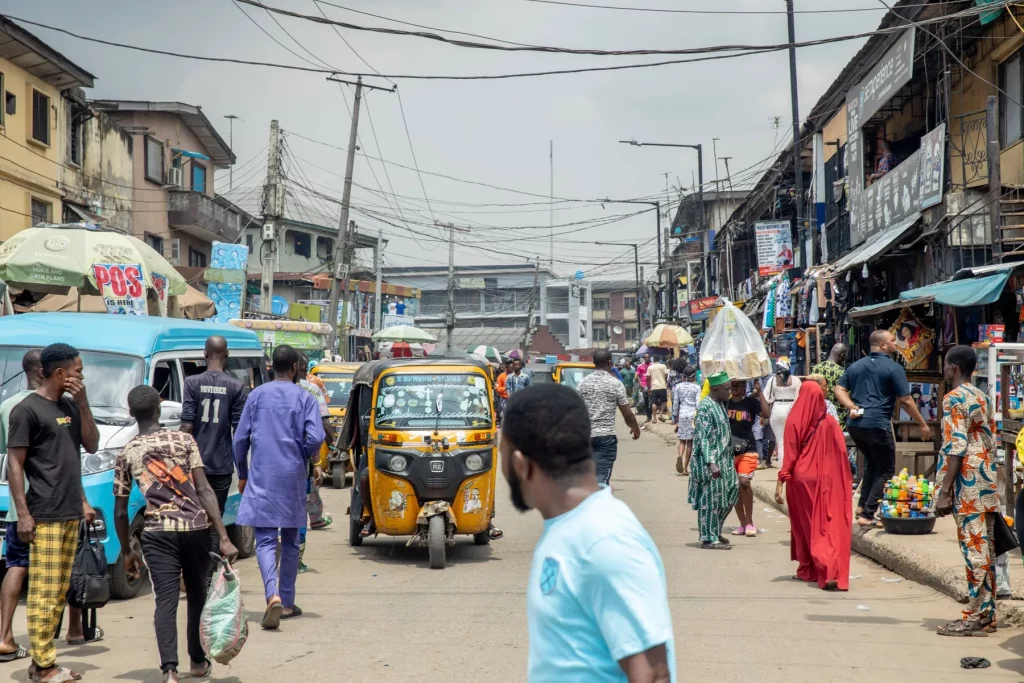
Nigeria’s rapid growth in formal financial inclusion has not translated into proportional credit access, recent data shows. While 73 percent of adults now hold a formal financial account, only 10 percent have obtained a loan from a regulated lender, highlighting a deep disconnect between bank ownership and borrowing power.
What Happened
According to the 2026 Access to Financial Services in Nigeria (A2F) survey by EFInA, formal financial inclusion rose to 73 percent, up from 64 percent in 2023. The share of adults excluded from the financial system fell from 26 percent to 21 percent, meaning roughly 87.2 million Nigerians are now formally included. Yet only about 12 million, or 10 percent, access formal credit. The Central Bank of Nigeria reports that outstanding consumer credit declined from ₦4.72 trillion ($3.5 billion) in 2024 to ₦3.78 trillion ($2.8 billion) in 2025, a drop of nearly 20 percent. Meanwhile, the monetary policy rate remained between 27 and 27.5 percent, making funding expensive for lenders. Informal borrowing remains common, with 16 percent of adults sourcing credit from non-formal channels and 10 percent relying on family and friends.
Why This Matters
The gap between inclusion and credit has real consequences for individuals and the broader economy. High inflation erodes purchasing power, leaving many Nigerians with less disposable income to service debt. EFInA found that 59 percent of respondents would struggle to raise ₦156,000 within seven days, indicating limited financial buffers to cover unexpected expenses or loan repayments. For lenders, the environment is equally challenging: the Central Bank reported an 8.03 percent non-performing loan ratio in January 2026, meaning roughly ₦8 of every ₦100 in bank loans is overdue by 90 days or more. Digital lenders have expanded mobile-based borrowing, but faster decisions do not eliminate risk. OPay’s 2025 lending portfolio, for example, generated $260.25 million in financing revenue against $121.29 million in credit loss provisions, illustrating how much revenue must be allocated to anticipated defaults. International comparisons underscore the challenge: Brazil, China, Kenya, and South Africa all show higher formal borrowing rates than Nigeria despite similar account ownership, suggesting that credit infrastructure, not just account access, drives loan participation.
Key Takeaways
- Financial inclusion and credit access are distinct metrics; owning a bank account does not guarantee loan eligibility.
- High interest rates, inflation, and limited credit histories are the primary barriers keeping formal credit out of reach for most Nigerians.
- Lenders must balance risk and cost, often allocating nearly half of financing revenue to expected credit losses, as OPay’s figures illustrate.
- Improving credit information systems, designing loan products that match borrower cash flows, and reducing inflation are essential to narrowing the gap.
- Without affordable credit, the benefits of formal inclusion—such as shock absorption, livelihood investment, and major expense management—remain out of reach for the majority.
Conclusion
Nigeria’s financial inclusion story is one of progress, but scale alone will not deliver economic opportunity. True impact requires moving beyond surface-level account growth to build a credit ecosystem that is both repayable for borrowers and sustainable for lenders. As inflation eases and credit infrastructure strengthens, the promise of accessible, affordable loans can finally move from aspiration to reality.


Discussion
Join the conversation
Thoughtful reactions, questions, and follow-up ideas help shape the next story.