Introduction
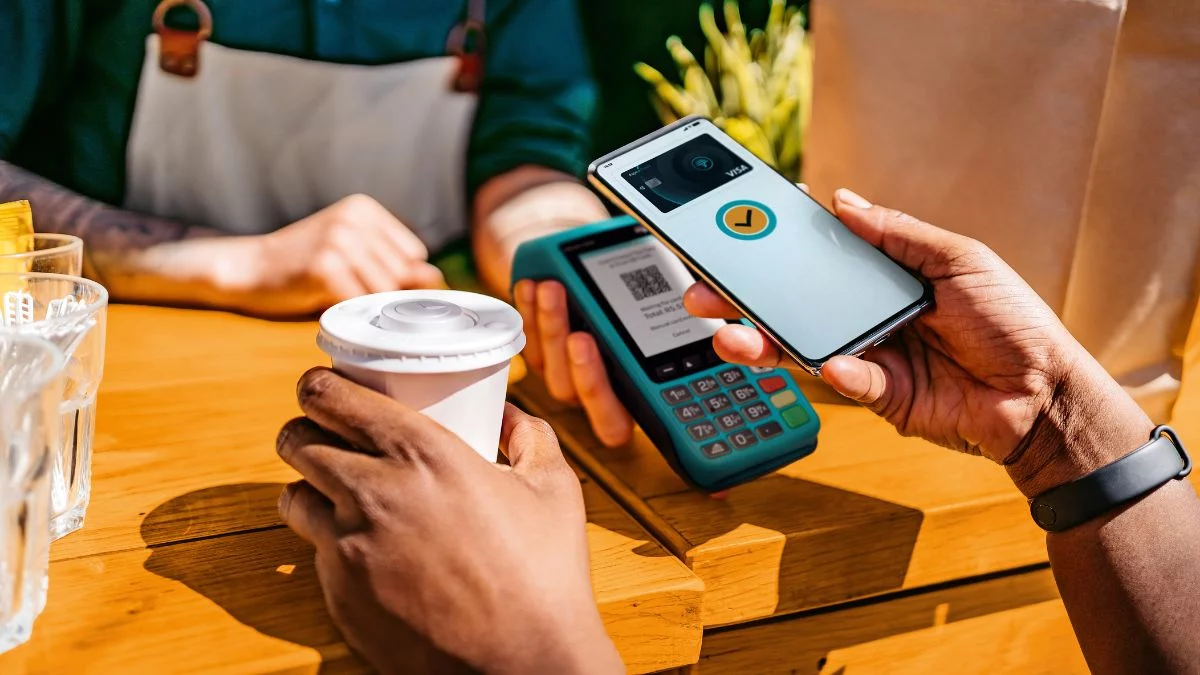
South African fintechs are engaged in a high-stakes competition to capture daily consumer spending and build lasting financial loyalty. The battle extends beyond opening accounts to becoming the primary platform where people receive, hold, and spend money each day.
What Happened
Bank Zero, the app-only lender, recorded its first break-even month in August 2026, five years after launch. Its alliance banking model lets partners offer financial services on its infrastructure, currently serving 275,000 direct customers and an additional 500,000 through partnerships like Mukuru. Meanwhile, MTN MoMo is working to convert its 317 million telecom subscribers into active financial users, reporting over 70 million monthly active across 14 markets as of September 2026. FNB Connect combines mobile connectivity with banking rewards, reporting R28.6 billion in customer value, an 18% increase. Mukuru, originally focused on cross-border remittances, is expanding into everyday payments and fund holding through Bank Zero's platform, aiming to transform periodic transfers into ongoing financial relationships.
Why This Matters
The fintech frontier is shifting from user acquisition to habitual engagement. Industry research identifies high transaction costs, fragmented collaboration, and limited payment interoperability as major barriers to everyday digital adoption. While established banks benefit from trust and network access, newer entrants must offer compelling reasons for consumers to change entrenched cash habits. Partnerships can accelerate growth, but reliance on another institution's infrastructure risks ceding control of the customer relationship. Sustainable revenue ultimately depends on whether growth translates into frequent transactions and repeat usage.
Key Takeaways
- Bank Zero's alliance model expands reach without direct customer acquisition costs.
- MTN MoMo's large subscriber base faces the critical gap between distribution and active usage.
- FNB Connect demonstrates how connectivity and rewards drive immediate customer value.
- Mukuru's expansion illustrates the remittance-to-banking transition model.
- Payment interoperability and affordable infrastructure are essential for widespread digital adoption.
- Habitual usage, not just account numbers, determines long-term fintech success.
Conclusion
The competition for South Africa's everyday payments is a test of infrastructure, consumer habits, and strategic partnerships. Platforms that move beyond surface-level integrations to deliver seamless, affordable, and widely accepted payment experiences will capture lasting loyalty. For investors and operators, the winners will be those who convert distribution into durable, repeatable financial engagement.


Discussion
Join the conversation
Thoughtful reactions, questions, and follow-up ideas help shape the next story.